Contact
 Help


Lehman Brothers Eighteen Years On

 BullionStar
 0 Comments


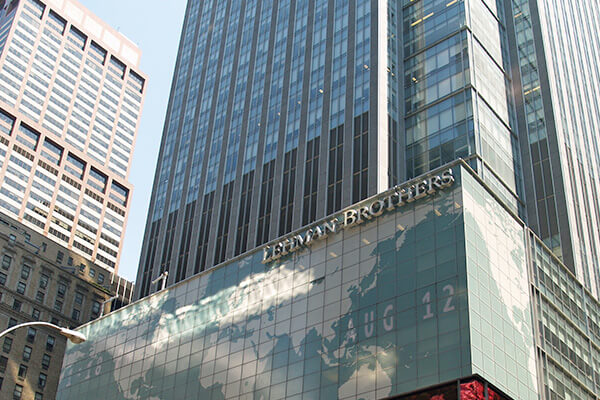
On Monday, 15th September 2008, Lehman Brothers filed for Chapter 11 bankruptcy. One of the US’s most established investment banks, founded in 1850, and with over 25,000 employees globally, had reached a point where its name, scale and history could no longer secure the confidence of its lenders.
For everyone protecting their savings, the collapse raises questions that remain relevant today, eighteen years later. How much of your own wealth depends on another institution being able to honour its promises, and what happens if that institution cannot pay when you need your money?
Physical gold offers a way to reduce the dependence. Understanding why starts with what failed at Lehman, what its collapse revealed about the wider financial system, and what it means to own an asset outright.
How confidence disappeared
Lehman’s failure grew out of a combination of property exposure, excessive leverage, and its dependence on short-term funding. It had combined large exposures to residential mortgages and commercial property with heavy borrowing, much of which was short-term, and had to be continually renewed. That left the firm vulnerable to falling asset values, and to lenders deciding that they no longer wanted to lend to them.
The mortgage securities at the centre of the wider subprime crisis depended on payments from underlying borrowers. Packaging loans into securities and assigning them credit ratings made it easier for them to sell, but it didn’t remove the risk that borrowers would stop paying. As the housing market deteriorated, investors started questioning what these securities were worth, and which institutions could swallow the losses.
Before its demise, Lehman’s leverage reached roughly 30:1, around thirty dollars of assets for every dollar of shareholder equity. At that ratio, a fall of around 3% in the value of its assets could eat up the equity supporting the business, the borrowing would still need to be repaid.
Yet even these numbers flattered the reality of the situation. In March 2010, the bankruptcy examiners report found that Lehman had used a repo variant known internally as “Repo 105" to window-dress its balance sheet at the end of each quarter. As the assets exchanged were worth at least 105% of the cash received, the transactions would be classified at sales, rather than borrowing. This allowed Lehman to move assets off its books days before reporting results, and buy them back in the days after.
Around US$39 billion was shifted this way at the end of 2007, US$49 billion in Q1 2008, and another US$50 billion the in second quarter. This manipulation was hidden, never disclosed to investors, rating agencies, regulators, or even their own board. The leverage the market could actually see was dangerous, but in reality it was much worse.
Leverage was only part of the problem. Lehman also financed assets that would take years to repay with borrowing that sometimes had to be renewed overnight. This included repurchase agreements, short-term funding secured against securities. If lenders became less confident in that collateral, they could demand more protection or decline to renew.
That distinction matters. A firm can own substantial assets and still lack the cash to meet payments. Selling assets quickly may require accepting below market prices, creating further losses and giving lenders another reason to withdraw.
The deterioration was visible before their ultimate collapse, and so were the reassurances:
- 10 September 2008 – Lehman pre-announce an estimated US$3.9 bullion quarterly loss. On the same call, it’s CFO tells investors that the firm capital position remains “strong".
- The same week – major rating agencies still rated Lehman ‘A’ – investment grade.
- Monday, 15 September 2008 – Lehman collapses, and files for Chapter 11, the largest bankruptcy in US history.
Five days from “strong" to gone.
The weekend a rescue failed
By the final weekend, Lehman needed a solution that could restore confidence before markets reopened. US authorities brought together the leaders of major financial institutions to arrange a private-sector rescue. No buy-out or support package sufficient to prevent bankruptcy was secured.
The distinction between liquidity and solvency had become critical. Emergency lending could supply cash against acceptable collateral, but it could not automatically repair a business whose capital was inadequate. In his subsequent testimony, Federal Reserve Chairman, Ben Bernanke, argued that Lehman needed substantial capital and an open-ended guarantee of its obligations, support the authorities lacked the power to provide at that time.
For investors, the episode exposed the danger of relying on an assumed rescue. The importance of an institution did not give its creditors an enforceable promise that it would be kept alive.
How one failure spread through the system
Lehman’s failure intensified a crisis that spread through banks and credit markets globally. The danger lay in the connections between institutions. A promise that once looked dependable could become difficult to collect when the institution behind it ran into trouble. It caused a financial contagion effect, which spread rapidly.
Institutions facing withdrawals required cash, lenders became more cautious about borrowers, and investors started questioning assets. The pressure on the system became even more strained.
The consequences quickly reached people who had never even bought a Lehman share. On 16th September, the Reserve Primary Fund, the world’s first money market fund which, at its peak held over US$60 billion in assets, announced that it valued its US$785 million of Lehman debt as worthless. Its net asset value fell to 97 cents per share, “breaking the buck”. With redemption requests exceeding US$40 billion in two days and no market willing to buy its remaining holdings at par, the fund stopped paying out and entered liquidation. A ‘low risk’ money market investment intended to preserve value had exposed savers to losses and restrictions on access.
On that same evening, the US Federal Reserve bailed out AIG for US$85 billion, fearing that another substantial failure would further hit credit markets and household wealth. From that day on, every bank deposit, money fund, or ‘safe’ asset was only as good as the government’s willingness to back it.
What we learned about financial safety?
What happened with Lehman exposed several distinctions that are easy to overlook when markets function normally. These are:
- Reputation is not a substitute for financial strength. A long history, recognisable name, or large balance sheet tell savers little about the quality of an institution’s assets, or indeed how urgently it needs more funding.
- The stated value of a holding and access to it are entirely separate questions. Someone may expect a product to preserve capital, yet find redemptions are delayed when the demand for cash rises. Access is a key part of financial safety.
- Separate investments can share the same weaknesses. Distribution across institutions, or product, may provide less protection than expected if they still depend on similar assets and funding markets.
- Ownership form matters. A bank deposit is an obligation for the bank to pay, a bond is an issuer’s promise to pay, an unallocated gold product generally represents a claim on a provider for metal. Each introduces a dependence on another party’s ability to uphold their end of the agreement.
Physical gold owned outright has no issuer that must remain solvent. Even in the case of vault storage, BullionStar simply remains a custodian, the metal itself does not require a borrower to repay a debt. That distinction is central to its appeal as a means of protecting wealth.
Dependence on emergency support
Post Lehman, banking rules did change. They were forced to hold more capital, and have stronger liquidity buffers, and the Basel Committee’s evaluation confirmed that reforms did improve resilience.
However, the need for intervention didn’t disappear. In March 2023, when Silicon Valley Bank and Signature Bank both failed, US authorities stepped in to protect all depositors through a “systemic risk exception”, including those above the normal insurance limit.
The distinction between different claims was explicit: depositors were protected, while shareholders and certain unsecured creditors were not. For uninsured depositors, protection depended on an exceptional policy decision.
The lesson is that stronger regulation can reduce the likelihood and impact of failure without removing the system’s dependence on emergency support. Savers still need to understand what they own, which protections apply and where those protections end.
Protecting the purchasing power of savings
Protecting the number on an account statement leaves a question unanswered: what will that money buy?
The years post-Lehman brought near-zero interest rates and quantitative easing. These policies sought to stabilise financial conditions whilst boosting economic activity. However, they also reduced the returns on savings. When deposit interest fell below inflation, balances could remain intact or even grow while purchasing power declined. They were designed to support borrowers, paid for by savers.
Under quantitative easing, central banks create reserves to purchase bonds. These purchases aim to lower longer-term interest rates and encourage spending and investment. For a saver, lower interest income can make it harder to keep pace with rising living costs.
With deposit rates pinned below inflation for close to a decade, balances stayed intact whilst purchasing power slowly got eroded away. Consider a saver earning 1% interest whilst inflation runs at 3%. After a year, their account balance is larger, but purchasing power is roughly 2% lower. This, repeated over years, whilst appearing as modest annual shortfalls, quickly becomes a substantial erosion of savings. No bank needs to fail for that loss to occur.
The post-pandemic inflation surge made the purchasing-power problem much more visible. Further monetary and fiscal support during the pandemic, disrupted production and supply chains, changing spending patterns and energy shocks all contributed to the economic conditions that followed.
For those saving towards retirement, trying to preserve wealth for the next generation, the concern is cumulative: whether money saved today will still buy what they need in the distant future. This becomes even harder to dismiss as public debt continues to grow pass US$40 trillion, and pressures mount to keep borrowing costs manageable, leaving savers exposed to the consequences.
Gold offers a way to hold part of one’s wealth independently. Its supply cannot be expanded by a central bank decision, and ownership does not depend on a government maintaining the purchasing power of a particular currency. Its market price still fluctuates, which makes its actual performance over the period important to examine.
What gold showed over eighteen years
Gold initially fell after Lehman as investors scrambled for cash and the dollar strengthened. By March 2009, it had recovered above pre-crisis levels and went on to make strong gains through much of 2011.
There were substantial corrections along the way. But gold’s monthly average rose from US$830 in September 2008 to US$4,411 in August 2026, more than a fivefold increase in its dollar price.
Throughout those gains and setbacks, physical gold required no issuer to repay it, no refinancing and no government rescue. Its price fluctuated; its existence did not depend on another institution surviving.
Central banks continue to recognise that value. They bought more than 1,000 tonnes annually from 2022 to 2024, followed by 863 tonnes in 2025. The institutions that issue currencies are themselves accumulating an asset they cannot create.
What, exactly, do you own?
For someone buying gold because of the lessons of Lehman, the next question is key: what, exactly, do you own?
Take a physically backed ETF, like GLD or IAU. Both hold allocated gold in trust, while investors hold shares in the fund. Ordinary shareholders cannot redeem their shares directly for gold bars. The ETF provides a mechanism for exposure to the gold price.
Gold mining shares introduce another set of risks. You own part of a mining business, whose performance depends on management, production costs (oil price etc), financing, the operational jurisdiction, as well as the gold price. Whilst they can offer upside, they do not provide direct ownership of gold.
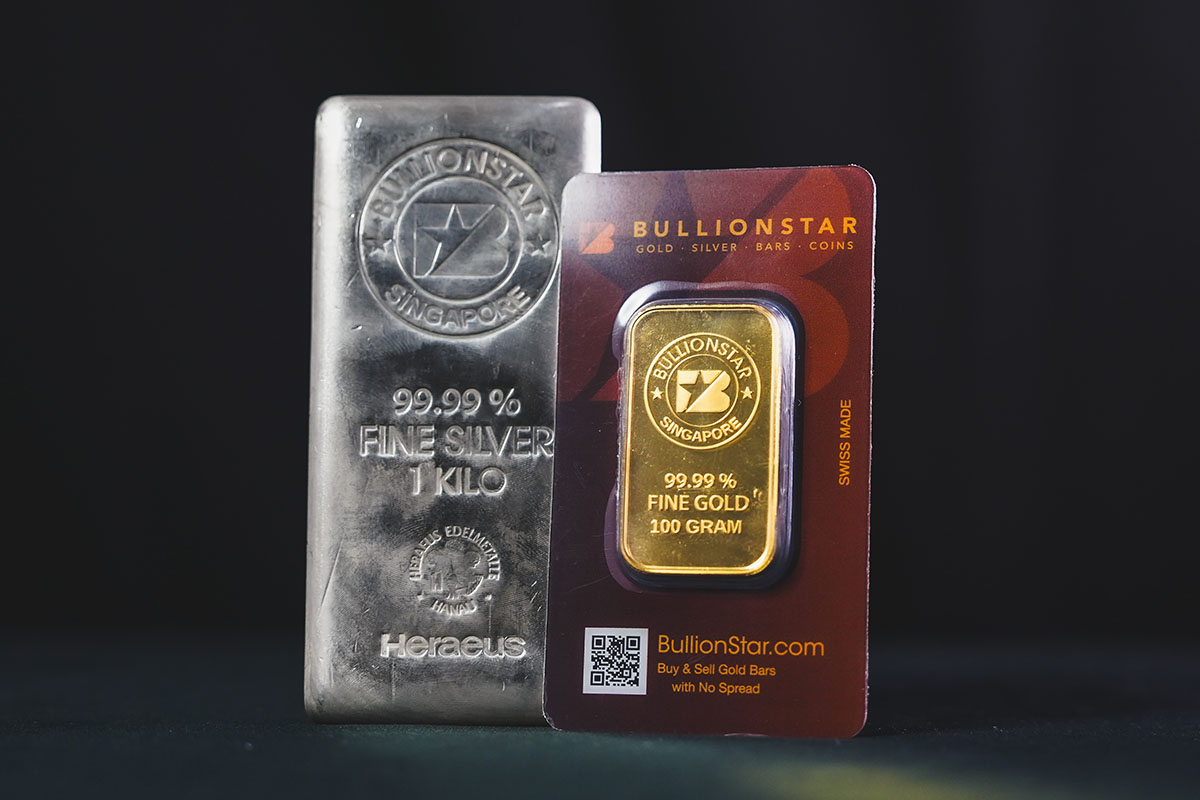
Physical bars and coins provide direct ownership. You take physical possession or use an allocated vault storage solution that holds your metal as a custodian. That is a meaningful choice, and if your objective is to reduce dependence on financial institutions, the legal ownership of the metal deserves as much attention as its price.
The lesson worth carrying forward
What happened with Lehman Brothers exposed how much of the financial system depends on obligations being honoured and confidence holding together. Whilst the reforms that followed the collapse improved resilience, they did not remove the dependencies.
For savers, there are two questions to ponder: will the institution holding my money be able to repay me, and what will that money be able to buy when it does?
Physical gold provides a way to hold part of your wealth outside that chain of repayment promises. Its ownership remains clear. You do not need to predict the next banking failure to see the value in that independence. Eighteen years after Lehman, that remains a compelling reason to own physical gold.
Popular Blog Posts by BullionStar
 How Much Gold is in the FIFA World Cup Trophy?
 Essentials of China's Gold Market
 Singapore Rated the World’s Safest & Most Secure Nation
 Infographic: Gold Exchange-Traded Fund (ETF) Mechanics
 BullionStar Financials FY 2020 – Year in Review
 Jim Rogers on Why He’ll Never Sell His Gold and Silver, the Fate of the Dollar, and the Complacency That Worries Him
 Why Gold & Silver Jumped Overnight
 The Gold Paradox: One Price, Two Markets
 Deep Dive: China’s Exit from Retail Paper Gold Trading — Why Beijing Is Curtailing Leverage, Not Gold Ownership
 Doug Casey on Gold Becoming Money Again, Political Risk, and Why He’s More Bullish on Silver