 Contact
 Help




Chinese Gold Market: How the World’s Largest Gold Market Works


China is the largest gold market in the world. It is the biggest producer of gold, mining around 380 tonnes in 2025. It is also the biggest consumer, with Chinese buyers taking 950 tonnes of gold in jewellery, bars and coins that year. Almost all of that gold passes through one institution: the Shanghai Gold Exchange, the world’s largest exchange for physical gold. The market is overseen by the People’s Bank of China (PBoC), the central bank, which controls who can import gold and holds more than 2,000 tonnes of official gold reserves.
The market has changed a lot in recent years. Chinese investors have moved decisively from jewellery to investment gold. In 2025, purchases of gold bars and coins overtook jewellery for the first time, making up more than half of all gold consumption in the country. Imports have surged too. In the first eight months of 2026, China imported over 1,100 tonnes of gold, more than in the whole of 2025. The PBoC has also been adding to its reserves month after month. Together, these trends have made Chinese demand one of the most important forces in the global gold market.
The Chinese market is also one of the most tightly controlled in the world. Only a small number of licensed banks can import gold, exports of gold bullion are generally prohibited, and most domestic gold must be traded through the Shanghai Gold Exchange. This guide explains how the market developed and how gold is imported and traded in China. It then covers what drives Chinese demand, where China’s gold comes from, and the bars and coins Chinese buyers invest in, including the Chinese Gold Panda.
Highlights
- China is the world’s largest gold producer and consumer, with 381 tonnes mined and 950 tonnes consumed in 2025.
- The Shanghai Gold Exchange, set up by the People’s Bank of China in 2002, is the world’s largest physical gold exchange and the main channel for China’s gold supply.
- Only PBoC-licensed banks and a few approved companies can import gold, and exports of gold bullion are generally prohibited.
- In 2025, Chinese purchases of gold bars and coins overtook jewellery for the first time, and imports hit record levels in 2026.
- The Chinese Gold Panda, first issued in 1982, is China’s official gold bullion coin and one of the few gold products exported from China.
Chinese Gold Market at a Glance
| Regulator | People’s Bank of China (PBoC) |
| Main physical exchange | Shanghai Gold Exchange (SGE), since 2002 |
| Gold futures | Shanghai Futures Exchange (SHFE), since 2008 |
| International access | SGE International Board (since 2014) and SGE vault in Hong Kong (since 2025) |
| Gold imports | Only PBoC-licensed banks and a few approved companies; imported bullion must be sold through the SGE |
| Gold exports | Bullion exports generally prohibited |
| VAT | Standard gold traded on the SGE is VAT-exempt; jewellery is taxed |
| Standard gold bar sizes | 50 g, 100 g, 1 kg, 3 kg and 12.5 kg |
| Mine production | 381 tonnes (2025) |
| Gold consumption | 950 tonnes (2025): 504 t bars and coins, 364 t jewellery |
| Official gold reserves | 2,366 tonnes (mid-2026) |
| Industry body | China Gold Association |
| Flagship bullion coin | Chinese Gold Panda (since 1982) |
China’s Gold Market: Size and Structure
China’s gold market is large, and it is also closely managed. China produces and consumes more gold than any other country. Its market is built around a single exchange and overseen by the central bank. That structure is quite different from the open, over-the-counter markets of London and Singapore, and it explains much of how gold moves into, around and out of China.
The People’s Bank of China (PBoC) sits at the top of the market. As well as managing China’s official gold reserves, it sets the rules for the domestic gold market. It decides which institutions can import gold, and it supervises the exchange where most gold is traded. The PBoC created that exchange, the Shanghai Gold Exchange (SGE), in 2002 as part of opening up the gold market. The SGE is now the world’s largest physical gold exchange. Gold mined in China and gold imported from abroad must be sold through the SGE in the form of standard bars, so its vaults act as the main channel through which gold reaches Chinese refiners, jewellers, banks and investors. Since 2016, the SGE has also set the Shanghai Gold Benchmark Price, a yuan-denominated price set twice a day.
Gold futures trade separately on the Shanghai Futures Exchange (SHFE), which launched its gold contract in 2008 and is regulated by the China Securities Regulatory Commission. Large state-controlled commercial banks connect the two exchanges with the public. These include the Industrial and Commercial Bank of China (ICBC), Bank of China, China Construction Bank and Agricultural Bank of China. They hold most of the gold import licences, trade on the SGE, and sell gold bars and gold savings products to millions of customers. Some of them also trade in the international market, including in London. Alongside them, the China Gold Association represents miners, refiners and jewellers and publishes the official figures for China’s gold production and consumption.
For the latest gold price in Chinese yuan, and the most recent Shanghai Gold Benchmark Price, see our gold price chart.

A Short History of China’s Gold Market
Gold has a long history in China, but the modern market is only about two decades old. In the 1930s and 1940s, Shanghai was East Asia’s largest centre for gold trading. In 1946, the International Monetary Fund named the Central Bank of China in Shanghai as one of its official gold depositories. That role ended with the civil war. In 1949 the Nationalist government moved China’s official gold reserves to Taiwan, and the new People’s Republic banned private ownership of gold and took control of the gold trade.
For the next three decades, the state controlled every stage of the gold market, from mining to sales. The first steps towards reform came in the early 1980s. In 1982 China launched the Gold Panda coin. In 1983 the State Council issued formal regulations on the control of gold and silver, with the PBoC buying and allocating all gold in the country.
The market began to open up in 2001, when the PBoC announced it would end its monopoly on gold trading. The Shanghai Gold Exchange opened in October 2002, giving banks, refiners and jewellers a central place to trade gold for the first time. From 2004, individuals could again buy gold bars for investment. The Shanghai Futures Exchange launched gold futures in 2008. In 2014, the SGE opened its International Board in the Shanghai Free Trade Zone, allowing foreign banks and traders to take part in the Chinese gold market. In 2025, the SGE opened its first vault outside mainland China, in Hong Kong.
Gold Exchanges in China
China’s gold trading takes place mainly on two exchanges in Shanghai. The Shanghai Gold Exchange is a physical market. Its main contracts are for standard gold bars that buyers can withdraw from SGE vaults. It is also where most of China’s physical gold supply and demand meet. Its domestic market, known as the Main Board, is open to Chinese banks, refiners, jewellers and other members, and individuals can trade through accounts at member banks. In 2014 the SGE added an International Board, based in the Shanghai Free Trade Zone. It lets foreign banks, refiners and traders buy and sell gold in yuan and store it in a vault that is treated as outside China for customs purposes.
The Shanghai Futures Exchange offers gold futures, which are mainly used for hedging and speculation, not for buying physical metal. The SHFE’s 1 kilogram gold contract is one of the most actively traded gold futures contracts in the world, second in importance only to COMEX in New York. The SGE has also extended its reach beyond the mainland. In 2025 it opened a delivery vault in Hong Kong, the first outside mainland China, which links its international contracts to the Hong Kong gold market. Ronan Manly examines what this means for global gold markets in China’s Golden Gateway.
| Venue / Product | Launched | What It Offers |
|---|---|---|
| SGE Main Board | October 2002 | Physical spot and deferred-delivery gold contracts in yuan, for domestic members and individuals through member banks |
| SHFE gold futures | January 2008 | 1 kg gold futures contract, regulated by the China Securities Regulatory Commission |
| SGE International Board | September 2014 | Yuan gold contracts for international members, with a vault in the Shanghai Free Trade Zone |
| Shanghai Gold Benchmark Price | April 2016 | Twice-daily yuan gold price set by auction on the SGE |
| SGE Hong Kong vault | June 2025 | Delivery vault in Hong Kong for SGE International Board contracts |
For more on how the SGE works, including its contracts, members and trading sessions, see our guide to the Shanghai Gold Exchange.
How Gold Is Imported and Traded in China
China imports a large share of the gold it uses, but it controls closely who can bring gold into the country and where that gold goes once it arrives. These rules keep most of the country’s gold supply passing through the Shanghai Gold Exchange, and they explain why gold that enters China rarely leaves.
Gold Imports and Import Licences
Only institutions licensed by the PBoC can import gold bullion into mainland China. In practice, this means a small group of large Chinese commercial banks and the Chinese subsidiaries of a few foreign banks, such as HSBC, Standard Chartered and ANZ. A handful of other companies, notably mining group Zijin, have also been approved. Each import needs PBoC approval, and imported standard gold has to be sold through the SGE before it can be used in the domestic market. Gold imported for the SGE International Board can instead be held in its Shanghai Free Trade Zone vault, which is treated as outside China for customs purposes, and only moves into the domestic market through a licensed bank. For the full rules, see our guide to China’s cross-border trade rules on gold.
Most of China’s imported gold comes from Switzerland, Hong Kong, Australia and the UK, often after being recast into kilobars at refineries abroad. Imports have reached record levels in 2026. China imported more than 1,100 tonnes of gold in the first eight months of the year, more than in the whole of 2025. Strong investment demand, a stronger yuan and gold prices in Shanghai trading above international prices all helped draw metal into the country. That gap is often called the “Shanghai premium”. Because imports are tightly controlled, arbitrage can’t close it quickly, so it is often watched as a signal of Chinese demand.
Standard Gold and the SGE
The SGE trades “standard gold”: bars and ingots of 50 grams, 100 grams, 1 kilogram, 3 kilograms and 12.5 kilograms, made by SGE-approved refiners at purities of 99.5% to 99.99%. Gold mined in China and imported bullion must be sold through the SGE in this form. Once a standard bar is withdrawn from an SGE vault, it can’t be redeposited without first being remelted, recast and assayed by an approved refiner. This rule protects the integrity of gold held in SGE vaults, much as the LBMA’s chain of custody does in London. It also means that withdrawals from SGE vaults give a useful measure of how much gold is leaving the wholesale market for jewellers, investors and other buyers each year.
Gold Exports
Exports of gold bullion from mainland China are generally prohibited. The exceptions are narrow. They include gold processed in free trade zones for re-export and some coins, including the Chinese Gold Panda. As a result, gold that enters China tends to stay there, which is one reason Chinese demand has such a strong effect on global supply. Travellers carrying gold out of China are subject to customs limits and declaration rules.
VAT on Gold in China
China’s value-added tax (VAT) rules give standard gold traded on the SGE favourable treatment compared with gold sold off the exchange. That is one reason so much of China’s gold supply flows through the SGE. Gold jewellery and other products sold to consumers are taxed. China revised its rules on gold VAT in November 2025. For a full explanation, see our guide to China gold tax and VAT, and for a comparison with other Asian markets, see Gold Tax and VAT Across Asia.
Chinese Gold Demand: Jewellery, Investment and Central Bank
Chinese gold demand comes from three main sources: jewellery buyers, investors and the central bank. For most of the past two decades, jewellery was the largest. That changed in 2025. According to the China Gold Association, purchases of gold bars and coins rose 35% to 504 tonnes, while jewellery demand fell by almost a third to 364 tonnes. It was the first time investment gold had overtaken jewellery in China. The shift reflects record gold prices, which made heavy jewellery more expensive, along with weak property and stock markets and low interest rates on savings. Together, these pushed Chinese households towards gold as a store of value.
Chinese Jewellery Demand
Jewellery is still central to Chinese gold culture. Chinese buyers have traditionally preferred high-purity 24 karat gold, often sold as “zu jin” (足金) or 999 gold, priced by weight with a small fabrication charge. It is bought for weddings, festivals and as a form of savings as much as for decoration. In recent years, younger buyers have shown a taste for lighter, design-led pieces and for small gold items such as “gold beans”, tiny pieces of pure gold sold by the gram. These sit somewhere between jewellery and investment.
Chinese Investment Demand
Investment demand now comes through several channels. Individuals buy bars and coins from banks and jewellers, and hold gold through bank accumulation plans and gold exchange-traded funds (ETFs). Chinese gold ETFs added around 44 tonnes in the first eight months of 2026, according to SGE data. Institutions have joined in as well. In February 2025, China launched a pilot allowing ten insurance companies to invest up to 1% of their assets in gold, opening a new source of long-term demand. We cover what that means for investors in China’s move to allow insurance companies to own gold.
Chinese Central Bank Demand
The third source of demand is the PBoC. The central bank resumed reported gold purchases in November 2024 and has added to its reserves every month since, reaching 2,366 tonnes by mid-2026. Many analysts believe China’s true official holdings are higher than the reported figure, because some purchases may be made through other state entities or not reported straight away. For the full picture, see our guide to China’s gold reserves.

SGE Withdrawals vs Consumer Demand
Measuring Chinese gold demand isn’t straightforward, and different sources give very different answers. The China Gold Association and research firms such as Metals Focus, whose figures the World Gold Council uses, estimate consumer demand: what households buy as jewellery, bars and coins. Another measure is the amount of gold withdrawn from Shanghai Gold Exchange vaults, because almost all gold entering China’s wholesale market passes through the SGE.
For many years, the two measures have been far apart. In 2015, SGE withdrawals reached a record 2,596 tonnes, while consumer demand estimates were less than half that. In 2016, withdrawals were 1,970 tonnes, compared with the World Gold Council’s consumer demand figure of about 914 tonnes. The gap reflects demand that consumer surveys don’t capture, such as gold bought by institutions and banks, gold held as bank inventory and on bank balance sheets, and some double counting from recycled gold. BullionStar’s research has long argued that SGE withdrawals are a better guide to China’s total wholesale demand. See our analysis of gold demand within the Chinese gold market.
How Much Gold Do Chinese Households Own?
No official figure exists for the amount of gold held privately in China, and estimates depend heavily on their assumptions. One approach starts from an estimate of the gold China held in the 1990s. It then adds China’s mine output and net imports for each year since, on the basis that gold rarely leaves the country. Using this method, BullionStar analyst Koos Jansen estimated that private holdings in China had reached around 16,000 tonnes by mid-2017. Adding his estimate of official reserves brought the total to more than 20,000 tonnes of gold in China. With record imports and strong domestic production since then, private holdings today are likely to be substantially higher. Exact figures, though, remain estimates rather than measured data.
Gold Mining and Refining in China
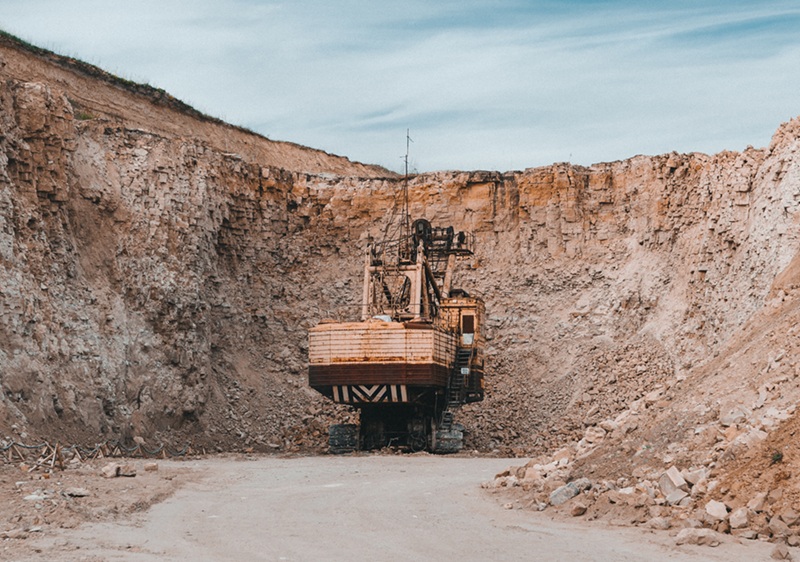
China has been the world’s largest gold-mining country since 2007. In 2025, its mines produced 381 tonnes of gold from domestic ore, according to the China Gold Association, ahead of Russia and Australia. Output peaked at around 478 tonnes in 2014 and then fell back. Older, lower-grade mines were closed, and tighter environmental rules reduced production in the years that followed. Most Chinese gold comes from dedicated gold mines. The rest is recovered as a by-product of copper and other metal mining. The largest producing region is Shandong province, especially the Jiaodong Peninsula.
The industry is dominated by a few large, mostly state-linked companies. Zijin Mining, Shandong Gold, China National Gold Group, and Zhaojin Mining are among the biggest producers. China National Gold also runs a large network of gold retail shops. Chinese miners have increasingly expanded overseas, buying mines in Africa, Central Asia, Latin America and elsewhere. Gold from these overseas operations can be shipped back to China for refining, which adds to the country’s imports as well as its supply.
Even as the world’s largest producer, China mines far less gold than it consumes. Domestic production meets well under half of demand, and the rest comes from imports and recycled gold. For more on China’s miners, reserves and production history, see our guide to Chinese gold mining.
Gold Refining in China
China has a large refining industry that turns mined gold, imported doré and scrap into standard bars for the SGE. Dozens of refiners are approved by the SGE to produce standard gold bars and ingots. Sixteen Chinese refiners are also on the LBMA’s Good Delivery List, so their bars are accepted in the international market. These include Great Wall Precious Metals, part of the state-owned China Banknote Printing and Minting Corporation (CBPM), along with refineries run by Zijin Mining and Shandong Gold. In 2015, the SGE and LBMA agreed on a common standard for 1 kilogram gold bars of 99.99% purity. This made it easier for kilobars refined in Switzerland, Hong Kong and elsewhere to flow into China.
Chinese Gold Bars and Coins
Chinese buyers have a wide choice of gold bars and coins. The range runs from standard exchange bars to small bank-branded bars and traditional ingot shapes. China also produces one of the world’s best-known gold bullion coins, the Gold Panda. For investors outside China, it helps to know what each type is, because they differ in purity, in how widely they are recognised and in how easily they can be sold.
Chinese Gold Bars
The bars at the heart of the Chinese market are the SGE standard bars traded on the Shanghai Gold Exchange. They come in 50 g and 100 g bars and 1 kg, 3 kg and 12.5 kg ingots. They are cast by SGE-approved refiners at purities from 99.5% to 99.99%. The 1 kilogram bar of 99.99% purity is the workhorse of the Chinese and wider Asian gold markets, and since 2015 it has followed a standard shared by the SGE and the LBMA.
Most Chinese individuals buy smaller retail bars from banks and jewellers. China’s large commercial banks sell their own branded gold bars, often in sizes from a few grams to 1 kilogram. Jewellery chains such as Chow Tai Fook and Lao Feng Xiang sell bars and wafers, often decorated with zodiac animals, festival themes or lucky characters. These bars are usually marked “足金” (zu jin, meaning full or pure gold) or “9999”, showing purity of 99.9% or 99.99%. You’ll also find bars sized in taels, the traditional Chinese unit of weight. The tael used in the Hong Kong gold trade is about 37.4 grams, while the mainland tael is now a metric 50 grams.
Then there is the yuanbao, the boat-shaped ingot known in English as sycee. In imperial China, sycee ingots of silver and gold were used as money. Today, small gold yuanbao are popular gifts at Chinese New Year and weddings and are seen as symbols of wealth and good fortune. Some are solid fine gold, but many decorative versions are gold-plated, so they should be checked carefully before buying.
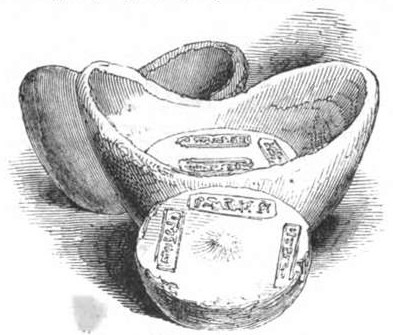
By Johann Jacob Weber (Hrsg.), 1803–1880 – Illustrirte Zeitung, Nr. 6 vom 5. August 1843, J. J. Weber, Leipzig 1843. MDZ München, Public Domain.
For investors outside China, the main question with Chinese bars is how easily they can be sold. Bars from refiners on the LBMA Good Delivery List are widely recognised. Bank and jeweller bars from other brands may only be accepted after testing, or may be bought back at a lower price. Ronan Manly looks at the markings on Chinese bars in Chinese Gold Bar Photos Lost in Translation, and our guide to gold purity explains the stamps used to show fineness.
The Chinese Gold Panda
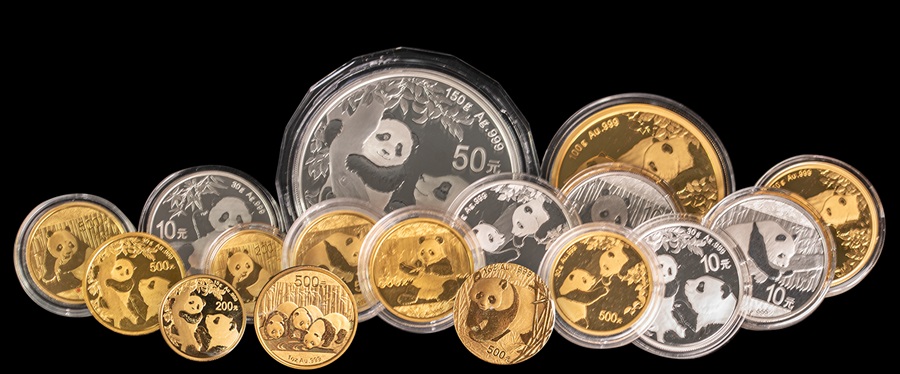
The Chinese Gold Panda is China’s official gold bullion coin. It was first issued by the People’s Bank of China in 1982, which makes it one of the oldest modern gold bullion coins. It is produced by the state-owned China Gold Coin Corporation at mints in Shanghai, Shenzhen and Shenyang. The Panda is struck in 99.9% fine gold, and it is legal tender in China with a face value in yuan.
The Panda stands out from other bullion coins in two ways. First, its reverse design changes every year, showing a new image of the giant panda, which makes Pandas popular with collectors as well as investors. Second, since 2016 it has been made in metric weights rather than troy ounces. The main sizes are 1 g, 3 g, 8 g, 15 g and 30 g, with the 30 g coin replacing the earlier 1 oz Panda. The Panda is also one of the few gold products that can be legally exported from China, which is one reason it is so widely traded abroad.
BullionStar stocks the current-year Gold Panda in a range of sizes, including the 2026 30 g Gold Panda and the 2026 1 g Gold Panda, as well as the 2026 30 g Silver Panda.
Frequently Asked Questions
How big is China’s gold market?
China has the largest gold market in the world. It is the biggest gold producer, mining 381 tonnes in 2025, and the biggest consumer, with 950 tonnes of jewellery, bar and coin demand that year. It is home to the Shanghai Gold Exchange, the world’s largest physical gold exchange. China imported more than 1,100 tonnes of gold in the first eight months of 2026, a record, and the People’s Bank of China held 2,366 tonnes in official reserves by mid-2026.
Does China import or produce most of its gold?
China imports more gold than it produces. Although it is the world’s largest gold miner, its 381 tonnes of mine output in 2025 met well under half of its demand. The rest comes from imports, mainly from Switzerland, Hong Kong, Australia and the UK, plus recycled gold. Imports reached record levels in 2026.
What is the role of the Shanghai Gold Exchange?
The Shanghai Gold Exchange (SGE) is China’s central market for physical gold. Set up by the People’s Bank of China in 2002, it is where mined and imported gold must be sold as standard bars before entering the domestic market. The SGE also sets the yuan-denominated Shanghai Gold Benchmark Price. Through its International Board and Hong Kong vault, it gives foreign members access to the Chinese gold market.
How much gold do Chinese households own?
There is no official figure for private gold holdings in China. One widely cited estimate by BullionStar analyst Koos Jansen put private holdings at around 16,000 tonnes in mid-2017, based on cumulative mine output and net imports. Since then, record imports and strong investment demand mean the true figure today is likely to be considerably higher.
Can foreigners buy gold in China?
Foreign visitors can buy gold jewellery and small gold bars from jewellers and banks in China. Direct trading on the Shanghai Gold Exchange is mainly for Chinese members and residents trading through member banks, while foreign institutions access the market through the SGE International Board. Because exports of gold bullion are restricted, many international investors buy Chinese gold products, such as the Gold Panda, outside China instead.
Can you take gold out of China?
Exports of gold bullion from mainland China are generally prohibited. Travellers leaving China are subject to customs limits and must declare gold above the permitted amount. Personal jewellery is treated differently from bullion. Chinese Gold Panda coins are one of the few gold products officially exported from China, and they are widely available from dealers abroad.
What is a Chinese Gold Panda coin?
The Chinese Gold Panda is China’s official gold bullion coin, first issued by the People’s Bank of China in 1982. It is struck in 99.9% fine gold, carries a new panda design every year, and since 2016 has been made in metric weights, with 30 g as the main size. It is legal tender in China and is popular with both investors and collectors.
Buying Chinese Gold Coins and Bars
China’s influence on the gold market keeps growing. Its record imports, the shift of its households from jewellery to investment gold, and a central bank that keeps adding to its reserves have made Chinese demand one of the main drivers of the gold price. For investors elsewhere, the Chinese market offers a useful lesson: Chinese buyers have long treated physical gold as savings to be held, not just traded.
Investors outside China can own Chinese gold directly through the Chinese Gold Panda. BullionStar stocks GST-free current-year Gold Pandas in sizes from 1 g to 30 g, alongside a wide range of gold bars and gold coins from LBMA-accredited refiners and national mints, including kilobars of the kind traded on the Shanghai Gold Exchange.
Many investors in Asia also choose where to hold their gold as carefully as what to buy. BullionStar is based in Singapore, and the Singapore gold market is another major gold hub in Asia. Customers can store their gold in our vault at Le Freeport. Stored metal is fully allocated and stays in the customer’s own legal ownership, and it can be collected from our Bullion Center, shipped internationally or sold back to BullionStar at live prices.
Subscribe to Gold University Articles
Copyright Information: BullionStar permits you to copy and publicize articles or information from the BullionStar Gold University provided that a link to the article's URL or to https://bullionstar.com is included in your introduction of the article or blog post together with the name BullionStar. The link must be target="_blank" without re="nofollow". All other rights are reserved. BullionStar reserves the right to withdraw the permission to copy content for any or all websites at any time.